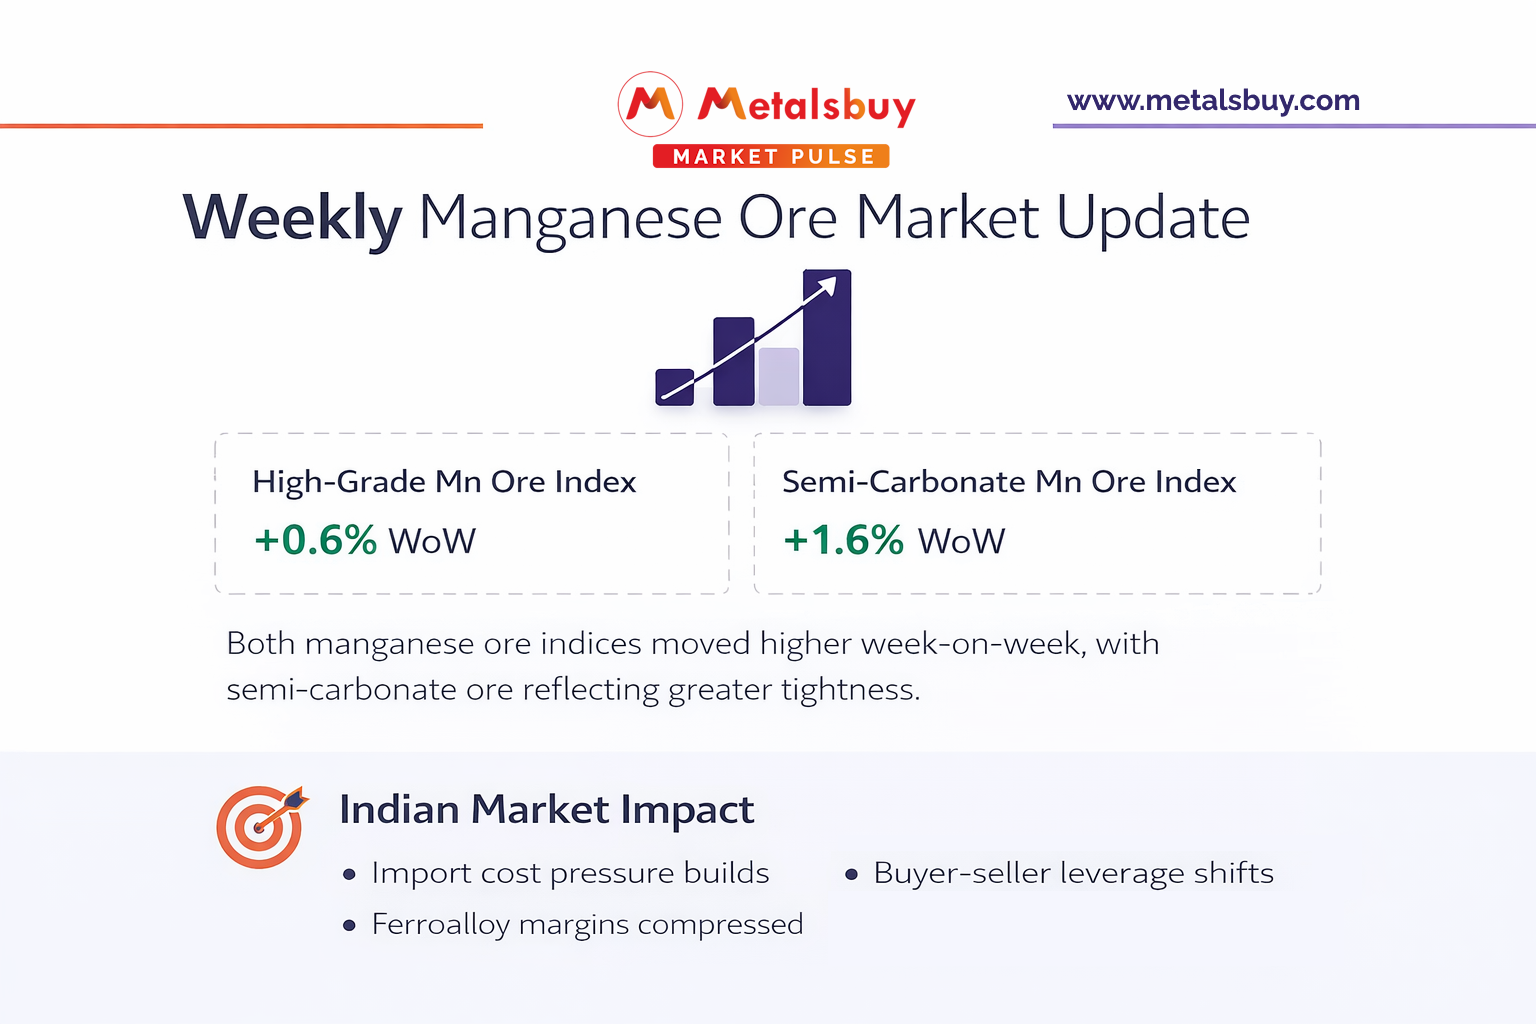
1. Weekly Index Movement: What Changed
The global manganese ore market recorded a firm week-on-week movement, with gains observed across key benchmark segments:
-
High-grade manganese ore registered a ~0.6% WoW increase, indicating early signs of price base stabilisation.
-
Semi-carbonate manganese ore (36.5% Mn) posted a stronger ~1.6% WoW rise, outperforming other grades and highlighting relative tightness.
While the magnitude of change remains moderate, the directional consistency across segments marks a notable shift from recent softness.
2. Why the Semi-Carbonate Segment Is Leading
The sharper rise in semi-carbonate manganese ore reflects structural sensitivity within this segment:
-
Lower spot availability compared with high-grade material
-
Faster response to marginal changes in demand
-
Higher dependence by cost-optimised alloy producers
The current movement suggests that even incremental buying activity is now translating into firmer benchmarks, reinforcing price stickiness.
3. Implications for the Indian Market
India’s manganese ore market is structurally exposed to global index movements, given its reliance on imported material for ferroalloy production.
a) Import Cost Transmission
-
A ~1.6% WoW rise in semi-carbonate benchmarks directly raises replacement cost expectations for Indian buyers.
-
Importers with uncovered near-term requirements face reduced negotiation headroom.
b) Pressure on Ferroalloy Margins
-
Alloy producers continue to operate under compressed spreads.
-
Rising ore input costs cannot be immediately passed through, leading to:
-
Deferred procurement
-
Smaller, more frequent purchases
-
Increased focus on blending optimisation
-
c) Buyer–Seller Dynamics
-
Sellers gain marginal leverage, particularly for prompt shipment cargoes.
-
Discount appetite has weakened compared with earlier weeks.
4. Demand Conditions: Stable but Disciplined
Demand indicators remain steady rather than expansionary:
| Indicator | Current Status | Trend |
|---|---|---|
| Alloy operating rates | Stable | → |
| Restocking activity | Selective | ↑ |
| Forward bookings | Limited | → |
| Spot enquiries | Improving | ↑ |
The market is being supported by operational demand, not speculative buying.
5. Supply-Side Assessment
Supply fundamentals remain balanced, with no signs of excess availability:
-
No aggressive selling pressure observed
-
Sellers maintaining disciplined offer levels
-
Limited spot surplus restricting downside correction
This balance has allowed incremental gains to hold rather than reverse.
6. Logistics and Delivery Considerations
Logistics reliability continues to influence purchasing decisions:
-
Indian buyers show preference for suppliers with assured shipment timelines
-
Any delay risk is increasingly priced into negotiations
-
Prompt cargoes command stronger acceptance
While freight has not emerged as a volatility trigger this week, its sentiment impact remains material.
7. Market Risk and Volatility Indicators
| Parameter | Current Reading |
|---|---|
| Volatility | Low |
| Downside risk | Limited |
| Upside momentum | Gradual |
| Supply disruption risk | Low |
| Demand shock risk | Moderate |
The current environment favours price consolidation with an upward bias.
8. Near-Term Outlook (India-Centric)
Over the next 2–3 weeks:
-
The manganese ore market is expected to remain range-bound but firm.
-
Semi-carbonate material is likely to continue outperforming, barring demand slowdown.
-
Indian buyers are expected to maintain hand-to-mouth procurement, though replacement cost pressure may encourage phased buying.
Downside risks appear capped unless alloy production cuts emerge.
9. MetalsBuy Insight
This week’s manganese ore movement is less about headline gains and more about directional confirmation.
-
The ~0.6% rise in high-grade material signals downside exhaustion.
-
The ~1.6% rise in semi-carbonate ore highlights where real cost pressure is building, especially for India.
For Indian market participants, the signal is clear:
the market is transitioning from soft to stable, with early signs of upward consolidation.