Key Numbers
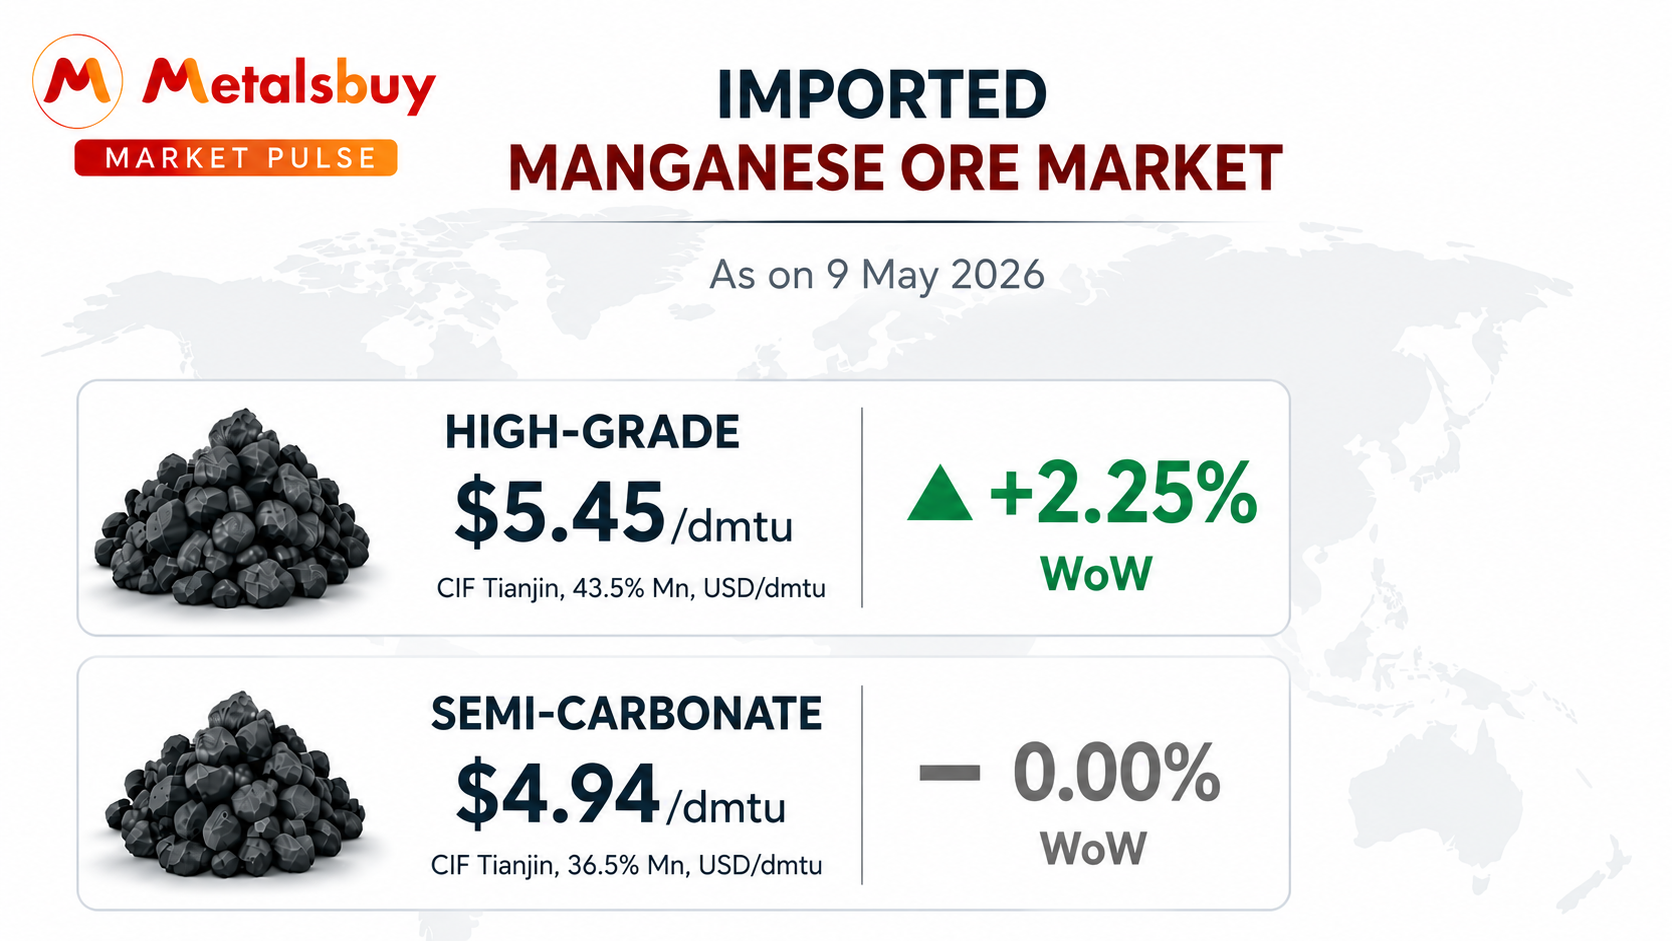
- High Grade Ore Index (43.5% Mn, CIF Tianjin): ↑ 2.25% WoW to $5.45/dmtu
- Semi-Carbonate Ore Index (36.5% Mn, CIF Tianjin): Flat WoW at $4.94/dmtu
- High-grade ore continues to outperform lower-grade material
- China spot buying improved selectively amid controlled alloy production
- Traders report tighter prompt availability for premium-grade cargoes
- Sentiment supported by stable port activity and disciplined offers
Market Analysis
The imported manganese ore market regained bullish momentum this week, with the High Grade Ore Index (43.5% Mn, CIF Tianjin) rising 2.25% week-on-week to $5.45/dmtu, while the Semi-Carbonate Index (36.5% Mn, CIF Tianjin) remained unchanged at $4.94/dmtu as buying activity remained concentrated in premium-grade material.
The latest movement indicates that supply-side tightness in higher-grade ore is once again emerging as the dominant market driver, even as downstream alloy demand continues to remain cautious. Chinese buyers were seen showing stronger preference toward high-grade cargoes due to better manganese recovery and operational efficiency, especially at a time when ferro alloy producers are operating under continued margin pressure.
After last week’s relatively cautious market tone, spot activity improved moderately during the current week as several traders reported selective restocking inquiries from alloy producers and trading houses. Although transaction volumes were not exceptionally aggressive, sellers maintained firm offers for premium-grade ore cargoes, reflecting confidence in near-term market support.
The premium segment continues to benefit from relatively tighter seaborne availability. Market participants indicate that arrivals of preferred high-grade brands from key exporting regions such as Gabon and South Africa remain controlled, while prompt cargo availability at Chinese ports is still not sufficient enough to trigger downward pressure on prices.
At the same time, lower-grade and semi-carbonate material continued to face balanced-to-ample availability at ports, limiting upside movement in that category. This divergence between high-grade and lower-grade ore reflects the increasingly selective procurement strategy being adopted by Chinese alloy smelters.
China’s ferro alloy sector remains the key factor influencing overall manganese ore demand. While discussions around production discipline and partial output cuts continue in certain alloy-producing regions, many producers appear to be maintaining cautious operations instead of undertaking aggressive shutdowns. This has kept procurement demand active, particularly for higher-efficiency ore grades.
Tianjin port activity also remained relatively stable during the week. Traders indicated that although buyers continued to negotiate aggressively, suppliers showed limited willingness to reduce offers for premium cargoes. Stable portside sentiment, combined with controlled inventories, has helped maintain overall confidence in the imported ore market despite ongoing uncertainty in downstream steel demand.
The market is also continuing to react to the structural supply concerns that emerged after global shipment disruptions witnessed over the past year. Since the industry experienced tighter ore availability from major mining regions, buyers have become increasingly sensitive to supply security risks. As a result, even moderate tightening in high-grade ore availability is now translating into stronger price reactions compared to historical market trends.
Meanwhile, China’s steel sector continues to provide mixed demand signals. Weakness in construction-linked steel consumption is still weighing on alloy sentiment, but expectations of infrastructure-linked support measures and seasonal procurement activity are preventing the market from entering a major correction phase.
Going forward, market participants are expected to closely monitor Chinese port inventories, alloy operating rates, and shipment flows from key exporting countries. Any further tightening in prompt high-grade cargo availability could continue supporting bullish sentiment in the near term.
For now, the imported manganese ore market appears to be stabilizing into a firm-to-positive trend, primarily driven by the continued strength in premium-grade ore.
Industry Impact
- Ferro alloy producers: Rising high-grade ore prices may further tighten silico-manganese production margins.
- Ore traders: Premium-grade cargoes are expected to maintain stronger bargaining power versus lower-grade material.
- Indian alloy manufacturers: Firm Chinese import sentiment could gradually influence seaborne offer levels into India.
- Steel sector: Stable alloy operating rates in China remain essential for sustaining current ore price momentum.