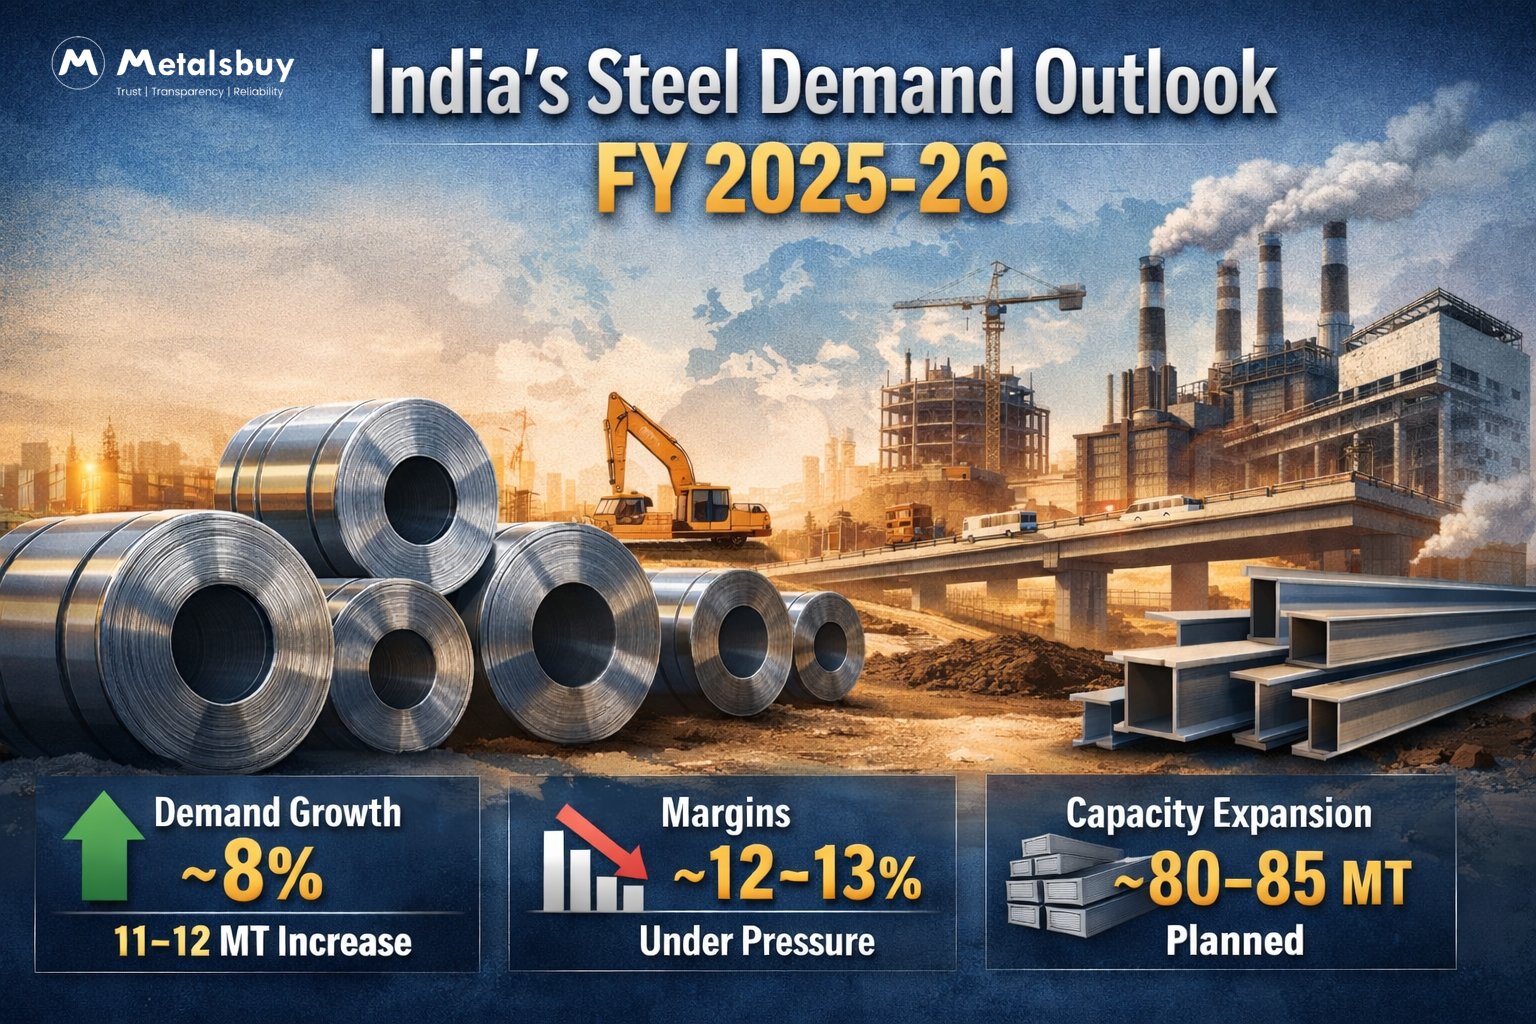
India’s steel industry is expected to continue its growth trajectory in FY2025–26, with domestic steel demand projected to rise by around 8% year-on-year, adding approximately 11–12 million tonnes of incremental consumption. The outlook reflects strong underlying demand drivers, particularly infrastructure and construction, even as the sector navigates pricing pressure and rising supply.
Demand Growth Supported by Infrastructure and Construction
Steel consumption growth in FY2025–26 is expected to be driven largely by government-led infrastructure spending, including roads, railways, metro projects, and urban development, alongside steady demand from housing and construction. These segments together account for a significant share of India’s steel usage and are expected to remain resilient.
India continues to stand out among major global economies as one of the fastest-growing steel-consuming markets, supported by policy focus on capital expenditure, manufacturing expansion, and long-term industrial development.
Pricing Environment Remains Challenging
Despite healthy volume growth, steel prices have struggled to maintain upward momentum. Domestic flat and long product prices corrected after earlier increases, reflecting heightened competition, increased availability, and global price weakness.
As a result, operating margins across the industry are expected to remain largely stable rather than expand, even as sales volumes improve. Margin improvement remains constrained by pricing pressure and the inability to fully pass on costs in a competitive market environment.
Capacity Additions Weigh on Market Balance
One of the key challenges facing the sector is the pace of capacity expansion. Significant capacity has been added over the last few quarters, with further additions expected in the near term. In the short run, this has led to a temporary supply-demand imbalance, exerting downward pressure on prices and realisations.
Over the medium term, the industry’s expansion pipeline remains sizeable, raising concerns around utilisation levels and the need for disciplined commissioning aligned with demand growth.
Global Factors Continue to Influence Domestic Prices
Global steel market dynamics continue to impact Indian prices. Weak demand conditions in some major international markets and excess global supply have kept export prices under pressure, limiting the scope for a sharp domestic price recovery.
While India’s strong internal demand provides some insulation, global trends continue to cap price upside and influence market sentiment.
Key Data Snapshot: India Steel Industry Outlook (FY2025–26)
| Indicator | Outlook / Estimate | Remarks |
|---|---|---|
| Steel Demand Growth | ~8% YoY | Equivalent to ~11–12 million tonnes of incremental demand |
| Primary Demand Drivers | Infrastructure, construction, housing | Public capex remains the key growth engine |
| Industry Operating Margins | ~12–13% | Expected to remain largely flat due to pricing pressure |
| Operating Profit per Tonne | ~US$105–110/tonne | Slight moderation compared to previous year |
| Domestic HRC Price Trend | Soft, below import parity | Prices corrected after earlier safeguard-led rise |
| Recent Capacity Additions | ~15 million tonnes | Added over the last 3–4 quarters |
| Near-term Capacity Pipeline | ~5 million tonnes | Expected to come on stream by FY-end |
| Medium-term Expansion Plans | ~80–85 million tonnes (next 5 years) | Large capex pipeline; utilisation discipline critical |
| Overall Sector Outlook | Stable | Strong demand offsets margin and supply challenges |
Outlook: Growth with Caution
Overall, India’s steel sector outlook for FY2025–26 remains stable, underpinned by robust demand growth and strong policy support. However, profitability is likely to remain under pressure as rising supply, global competition, and limited pricing power constrain margin expansion.
Going forward, steel producers focusing on cost efficiency, value-added products, prudent capacity utilisation, and balance sheet discipline are likely to be better positioned. While volumes are set to grow, earnings performance will depend on how effectively the industry balances expansion with market realities.
Sources
-
ICRA steel sector commentary
-
Industry disclosures and public market data
-
Metalsbuy market analysis