Key Highlights:
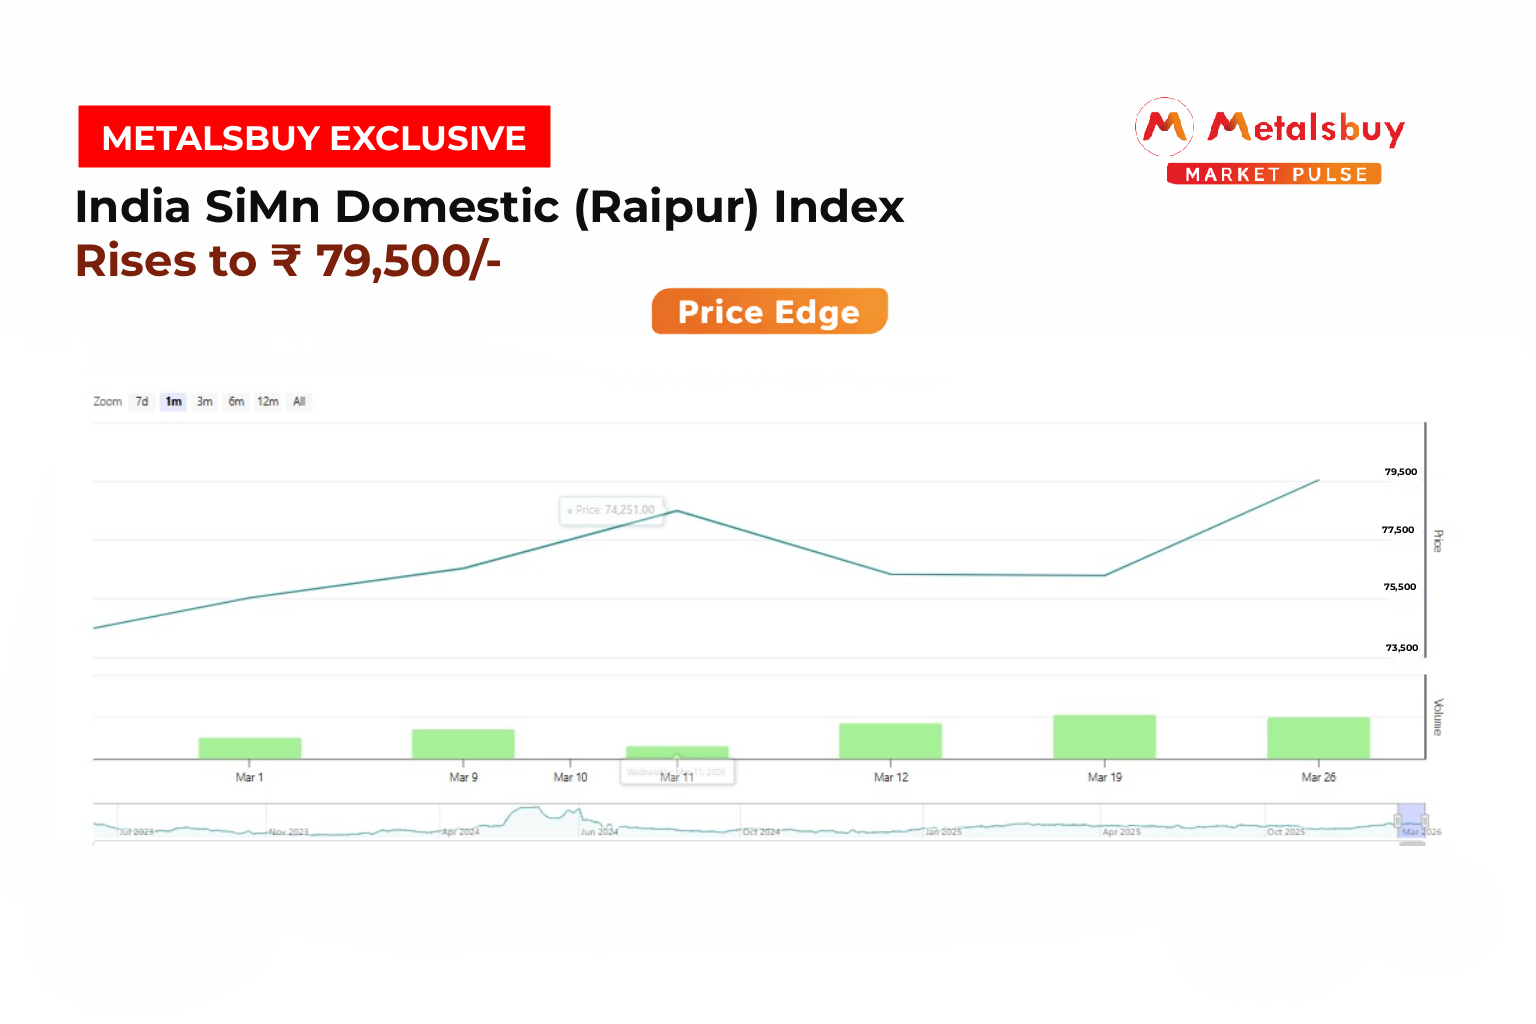
- Index Surge: SiMn (60/14) Ex-Raipur spot prices witnessed an unprecedented weekend rally, jumping by a direct ₹4,000/MT from Saturday's ₹75,500/MT to reach a staggering ₹79,500/MT today.
- Raw Material Squeeze: A sudden surge in imported manganese ore prices late Friday night has squeezed smelter margins, with market participants now bracing for expected price hikes from state-miner MOIL.
- Demand Spike: Despite the steep price jump, the market remains highly bullish. Buyers are actively ready to procure at the new elevated levels, rapidly draining spot inventory ahead of the new financial year.
- Upstream Steel Support: Resilient steel demand (Ex-Raipur MS billets holding at ₹41,500/MT) sustains relentless ferroalloy consumption.
- Energy Premium: Peak summer power tariffs continue to add ₹1,500–2,500/MT to baseline production costs.
Raipur, 30 March 2026: The domestic Silico Manganese (SiMn) market experienced one of its most volatile weekends in recent history, surging the benchmark Ex-Raipur index to ₹79,500/MT. While we typically reserve market assessments for Friday closing, the sheer aggression of this weekend's rally necessitated an immediate Monday intervention. The market witnessed a direct, massive ₹4,000/MT hike from Saturday’s closing level of ₹75,500/MT. This extraordinary upward trajectory is driven by a precise convergence of late-week supply shocks, highly aggressive buying behavior, and localized seasonal pressures.
Price Hike on Imported Manganese Ore
The foundational catalyst for the current rally is the sharp, overnight escalation in raw material costs. Late Friday night, international markets reported a sudden and steep spike in the Cost and Freight (CFR) prices of imported high-grade manganese ore. This immediate change in import prices completely altered the cost calculations for Indian ferroalloy smelters heading into the weekend. Furthermore, taking cues from this global surge, there is now a widespread market expectation that domestic state-miner MOIL Limited will also increase its prices for ferro grades in the near term. This undeniable and immediate cost-push inflation is being directly passed down to final SiMn spot prices.
Bullish Market Buying and Selling Behaviour
Market psychology is exceptionally bullish across central and eastern Indian hubs. Typically, a sudden ₹4,000/MT hike would stall trading; however, buyers are abandoning cautious approaches and are surprisingly ready to buy at the new ₹79,500/MT mark. Frantic pre-financial year procurement is driving this momentum, as consumers scramble to lock in deals to avoid potential mid-April spikes that could push well past current levels. Sellers, acutely aware of the tightening raw material supplies and the Friday night ore cost surge, are holding back bulk volumes, further widening the artificial spot deficit.
High Electricity Price Due to Increase in Consumption at Summer
Silico manganese smelting requires a massive 4,000 to 4,500 kWh of electricity per tonne. As India enters peak summer, surging power consumption has placed immense pressure on grids in hubs like Raipur and Durgapur. Industrial units face punitive peak-load tariffs or rely on expensive captive coal-based power generation. This summer-induced energy premium adds an estimated ₹1,500 to ₹2,500 to the base conversion cost, acting as a rigid floor that prevents producers from absorbing any additional raw material shocks.
Upper Movement in Steel Sector
SiMn demand is inextricably linked to the downstream steel sector, which is currently on a firm upward trajectory. Driven by pre-monsoon construction, integrated and secondary producers have ramped up capacity utilization. Benchmark MS billets (Ex-Raipur) are holding steady around ₹41,500/MT. Since steelmaking requires 14-16 kg of SiMn per tonne, this robust steel output translates directly into bulk domestic inquiries, meaning ferroalloy consumption remains relentless despite the steep hike.Market Outlook
The unique convergence of the Friday night imported ore price spike, expectations of impending MOIL price hikes, a resurgent steel sector, aggressive pre-financial-year procurement, and summer power tariffs forms the USP of today's market reality. The narrative has shifted to an immediate supply-side shock. With buyers fully willing to absorb the ₹4,000/MT weekend hike, those waiting for a near-term price correction may find themselves completely sidelined for the upcoming April-June quarter.
Market Outlook
The unique convergence of the Friday night imported ore price spike, expectations of impending MOIL price hikes, a resurgent steel sector, aggressive pre-financial-year procurement, and summer power tariffs forms the USP of today's market reality. The narrative has shifted to an immediate supply-side shock. With buyers fully willing to absorb the INR 4,000/MT weekend hike, those waiting for a near-term price correction may find themselves completely sidelined for the upcoming April-June quarter.